|
The Week Ahead: Highlights
Asia-Pacific Preview
China GDP, Industrial Production in Focus
By Brian Jackson, Econoday Economist
Chinas quarterly GDP release and monthly activity data for
the three months to September will be the focus in the Asia-Pacific region. GDP
growth slowed to a two-year low in the three months to June, largely reflecting
the initiial impact of the Iran conflict. Official monthly activity data and
PMI surveys indicate that conditions remained subdued in the three months to
September, with officials noting last month that "the adverse impact of
the external environment has intensified". GDP data will be accompanied by
monthly data for September, with the official PMI survey published earlier in
the month indicating close to zero growth in both the manufacturing and
non-manufacturing sector. Next weeks data will also be accompanied by
officials updated assessment of conditions and policy settings ahead of the
Peoples Bank of Chinas monthly review of loan prime rates.
The Bank of Koreas policy meeting is also scheduled in the
week ahead. Officials increased policy rates in both of their previous two
meetings, in mid-July and late August. They expect inflation to remain above
their two percent target "for a considerable time. Exchange rate
volatility and strong house price growth in Seoul were also cited as factors
supporting the case for tighter policy. Officials advised in August that
further rate hikes are likely in upcoming meetings, but CPI data released
earlier this month showed both headline and core inflation moderated in
September. Although another rate hike may be considered, the September
inflation data may provide scope for officials to wait for more information
before hiking rates again.
New Zealand inflation data will shape expectations for the
Reserve Bank of New Zealand policy meeting later this month. Headline inflation
rose from 3.5 percent to 4.1 percent in the three months to June. This is the
biggest increase in consumer prices since late 2023 and takes the headline
inflation rate well above the top of the RBNZ's target range of 1.0 percent to
3.0 percent. RBNZ officials have also increased policy rates in each of their
two previous meetings and advised that further policy tightening is likely in
the near term. Next weeks data would likely need to show a sharp moderation in
price pressures to shift the policy outlook.
Elsewhere in the region, Singapore and Hong Kong will report
inflation data for September, while Taiwan will report industrial production
data. Flash PMI survey data from India will give an early indication of October
conditions.
US Preview
Regional Fed Reports to Give Early Read on October
Business Conditions
By Theresa Sheehan, Econoday Economist
The communications blackout period around the October 27-28
FOMC meeting goes into effect at midnight on Saturday, October 17 and runs
through midnight on Thursday, October 29. As a result, Fed policymakers will
not be providing public remarks on monetary policy during the week. The most
important data in the week is likely to be relatively minor indicators that
reflect conditions in early October.
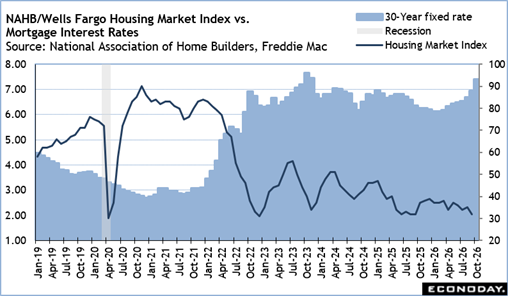
The NAHB/Wells Fargo housing market index for October at
10:00 ET on Monday will show how pessimistic homebuilders are with mortgage
rates running in the mid-7 percent range for a fixed rate mortgage. Gloomy
consumers worried about inflation, interest rates, and jobs are not heading
into the market for a new home, or an existing home for that matter. Whether a
home purchase is affordable at present is an issue for buyers, but also whether
buyers will continue to be able to meet the payments.
How the manufacturing and service sectors are faring in
October will weigh on the FOMC decision.
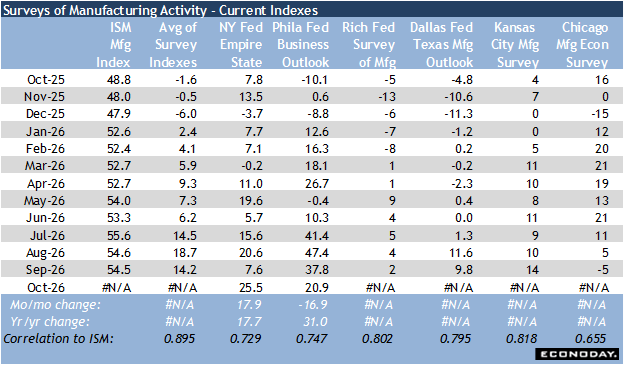
The manufacturing indexes for New York and Philadelphia have
already been released and point to modest-to-moderate expansion. The week sees
the Richmond manufacturing index at 10:00 ET on Tuesday, Chicago manufacturing
index at 8:30 ET on Thursday, and Kansas City at 11:00 ET on Thursday.
Richmonds composite index has been running just above neutral while Kansas
Citys has been on the rise to tempered expansion. The Dallas Feds
manufacturing index is not until Monday, October 26 at 10:30 ET. The Chicago index
indicates weaker conditions in the last few months.
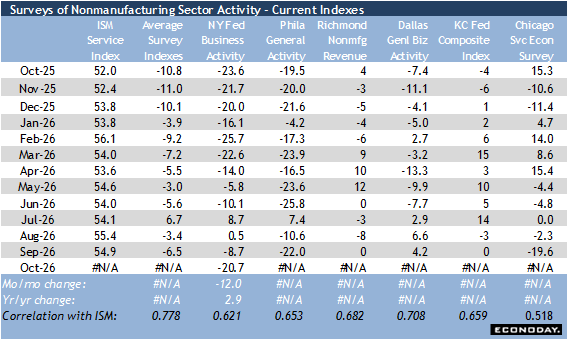
The indexes for the service sector in October will include
Philadelphia at 8:30 ET on Tuesday, Richmond at 10:00 ET on Tuesday, Chicago at
8:30 ET on Thursday, and Kansas City at 11:00 ET on Friday. The Dallas Fed
service sector survey is set for release at 10:30 ET on Tuesday, October 27.
Conditions for service sector are uneven due to the great variety of
businesses. Broadly speaking, the indexes are trending in a narrow range around
the neutral mark as they work to adapt to chaotic policy out of the federal
government, inflation, and a limited labor pool of skilled workers.
The Week Ahead: Econoday Consensus Forecasts
Monday
China Fixed Asset Investment for September (Mon
1000 CST; Mon 0200 GMT; Sun 2200 EDT)
Consensus Forecast, Year to Date on Y/Y Basis: -7.25%
Consensus Range, Year to Date on Y/Y Basis: -7.65% to
-7.3%
Fixed asset investment continues contracting with the
consensus looking for a decline of 7.25 percent on year in September, worse
than the 7.2 percent decrease in August.
China GDP for Third Quarter (Mon 1000 CST; Mon 0200
GMT; Sun 2200 EDT)
Consensus Forecast, Q/Q: 1.0%
Consensus Range, Q/Q: 0.7% to 1.1%
Consensus Forecast, Y/Y: 4.4%
Consensus Range, Y/Y: 4.0% to 5.2%
GDP expected to edge up to 4.4 percent rate on year in Q3
from 4.3 percent in Q2 with help from net exports.
China Industrial Production for September (Mon
1000 CST; Mon 0200 GMT; Sun 2200 EDT)
Consensus Forecast, Y/Y: 5.4%
Consensus Range, Y/Y: 4.8% to 5.5%
Industrial production expected to improve to a 5.4 percent
annual increase in September from 5.2 percent in August.
China Retail Sales for September (Mon 1000
CST; Mon 0200 GMT; Sun 2200 EDT)
Consensus Forecast, Y/Y: 0.5%
Consensus Range, Y/Y: 0.1% to 1.0%
The consensus sees annual sales growth edging up to 0.5
percent in September from 0.4 percent in August.
Canada CPI for September (Mon 0830 EDT; Mon 1230 GMT)
Consensus Forecast, CPI - M/M: 0.2%
Consensus Range, CPI - M/M: 0.0% to 0.4%
Consensus Forecast, CPI - Y/Y: 3.2%
Consensus Range, CPI - Y/Y: 3.0% to 3.3%
Consensus Forecast, Core CPI - M/M: 0.2%
Consensus Range, Core CPI - M/M: 0.2% to 0.2%
Consensus Forecast, Core CPI - Y/Y: 2.1%
Consensus Range, Core CPI - Y/Y: 2.0% to 2.4%
CPI is expected to show the effect of increasing energy
prices while food prices fall back. The consensus sees total CPI up 3.2 percent
on year versus 3.0 percent in August. The core is seen flat at 2.1 percent with
not much spillover from energy into other segments yet but everyone is watching
airfares.
US Housing Market Index for October (Mon 1000 EDT; Mon
1400 GMT)
Consensus Forecast, Index: 31
Consensus Range, Index: 30 to 32
Builder sentiment remains gloomy amid rising mortgage rates.
Consensus expectations call for the index down to 31 for October from an
already depressed 32 in September.
Tuesday
China Loan Prime Rate for October (Tue 0915
CST; Tue 0115 GMT; Mon 2115 EDT)
Consensus Forecast, 1-Year Rate - Change: 0 bp
Consensus Range, 1-Year Rate - Change: 0 bp to 0 bp
Consensus Forecast, 1-Year Rate - Level: 3.0%
Consensus Range, 1-Year Rate - Level: 3.0% to 3.0%
Consensus Forecast, 5-Year Rate - Change: 0 bp
Consensus Range, 5-Year Rate - Change: 0 bp to 0 bp
Consensus Forecast, 5-Year Rate - Level: 3.50%
Consensus Range, 5-Year Rate - Level: 3.50% to 3.50%
Chinese authorities continue to rely on fiscal measures
rather than rate cuts to boost the economy so no change expected from the PBOC
on loan prime rates.
UK Labour Market Report for October (Tue 0700 BST; Tue
0600 GMT; Tue 0200 EDT)
Consensus Forecast, ILO Unemployment Rate: 5.0%
Consensus Range, ILO Unemployment Rate: 4.9% to 5.0%
Consensus Forecast, Average Earnings - Y/Y: 3.8%
Consensus Range, Average Earnings - Y/Y: 3.6% to 3.8%
ILO unemployment expected up to 5.0 percent in October from
4.9 percent in September with earnings growth down to 3.8 percent from 3.9
percent.
Germany PPI for September (Tue 0800 CEST; Tue 0600
GMT; Tue 0200 EDT)
Consensus Forecast, M/M: 1.6%
Consensus Range, M/M: 0.3% to 2.0%
Consensus Forecast, Y/Y: 6.3%
Consensus Range, Y/Y: 5.0% to 6.4%
Energy prices are seen fueling a whopping 1.6 percent
increase in PPI on the month!
Germany ZEW Survey for October (Tue 1100 CEST; Tue 0900
GMT; Tue 0500 EDT)
Consensus Forecast, Economic Sentiment: 30.0
Consensus Range, Economic Sentiment: 25.1 to 33.0
Sentiment expected to fade to 30.0 in October from 34.7 in
September.
US Housing Starts and Permits for September (Tue 0830
EDT; Tue 1230 GMT)
Consensus Forecast, Starts - Annual Rate: 1.305 M
Consensus Range, Starts - Annual Rate: 1.250 M to 1.330
M
Consensus Forecast, Permits - Annual Rate: 1.385 M
Consensus Range, Permits - Annual Rate: 1.380 M to
1.391 M
Starts expected to recover to 1.305 million from 1.275
million in August but remain weak as affordability remains problematic.
US Pending Home Sales Index for September (Tue 1000
EDT; Tue 1400 GMT)
Consensus Forecast, M/M: 0.1%
Consensus Range, M/M: -0.5% to 0.5%
Home sales seen effectively flat with pending home sales
limited by high mortgage rates.
Wednesday
Japan Merchandise Trade for September (Wed
0850 JST; Tue 2350 GMT; Tue 1950 EDT)
Consensus Forecast, Balance: -78.00 B
Consensus Range, Balance: -368.90 B to 45.30 B
Consensus Forecast, Imports - Y/Y: 19.9%
Consensus Range, Imports - Y/Y: 17.7% to 20.1%
Consensus Forecast, Exports - Y/Y: 21.7%
Consensus Range, Exports - Y/Y: 17.9% to 24.0%
Based on provisional trade data for the first 20 days of
September by the Ministry of
Finance, export values are projected to rise 21.7 percent on
the year, marking the 13th
consecutive monthly increase, after rising 19.3 percent a
month earlier. In August, the
increase was led by automobiles, semiconductor-related
electronic components and
semiconductor production equipment.
Imports are expected to rise 19.9 percent on the year in
September after jumping 28.0 percent a
month earlier. In August, the increase was driven by crude
oil, semiconductor-related electronic components and computers, including
peripherals, as largely seen in recent
months.
UK CPI for September (Wed 0700 BST; Wed 0600
GMT; Wed 0200 EDT)
Consensus Forecast, M/M: 0.3%
Consensus Range, M/M: 0.2% to 0.4%
Consensus Forecast, Y/Y: 3.4%
Consensus Range, Y/Y: 3.3% to 3.5%
Consensus Forecast, Core CPI - Y/Y: 2.7%
Consensus Range, Core CPI - Y/Y: 2.6% to 2.8%
CPI seen up 3.4 percent on year in September with core up
2.7 percent.
Thursday
New Zealand CPI for March (Third Quarter) (Thu 1045
NZDT; Wed 2245 GMT; Wed 1745 EDT)
Consensus Forecast, Q/Q: 0.8%
Consensus Range, Q/Q: 0.7% to 0.9%
Consensus Forecast, Y/Y: 3.8%
Consensus Range, Y/Y: 3.7% to 3.9%
Annual inflation expected to recede to 3.8 percent in Q3
from 4.1 percent in Q2 as fuel costs are seen lower, offset by higher property
taxes, food and building costs.
South Korea Bank of Korea Announcement (Thu 1000 KST;
Thu 0100 GMT; Wed 2100 EDT)
Consensus Forecast, Change: 0 bp
Consensus Range, Change: 0 bp to 0 bp
Consensus Forecast, Level: 3.00%
Consensus Range, Level: 3.00% to 3.00%
After rate increases in July and August, the bank is
expected to leave rates unchanged. It helps that CPI has steadied while the
higher Korean won helps hold down import costs.
France Business Climate Indicator for October (Thu 0845
CEST; Thu 0645 GMT; Thu 0245 EDT)
Consensus Forecast, Index: 95.8
Consensus Range, Index: 95.0 to 96.0
Sentiment expected basically flat at a soft 95.8 in October
after dropping to 96.0 in September.
US Jobless Claims for Week of October 17 (Thu 0830
EDT; Thu 1230 GMT)
Consensus Forecast, Initial Claims - Level: 200 K
Consensus Range, Initial Claims - Level: 197 K to 202
K
Claims expected to continue hovering at historic lows in the
low hire, low fire economy.
Eurozone EC Consumer Flash for October (Thu
1600 CEST; Thu 1400 GMT; Thu 1000 EDT)
Consensus Forecast, Index: -17.0
Consensus Range, Index: -17.3 to -17.0
US Leading Indicators for September (Thu 1000 EDT;
Thu 1400 GMT)
Consensus Forecast, M/M: -0.2%
Consensus Range, M/M: -0.2% to -0.1%
The consensus sees a soft reading at minus 0.2 percent in
September.
US Kansas City Fed Manufacturing Index for October
(Thu 1100 EDT; Thu 1500 GMT)
Consensus Forecast, Level: 11.0
Consensus Range, Level: 7.0 to 12.0
The consensus sees the index slightly lower but in moderate
expansion at 11.0 in October from 14.0 in September.
Friday
Japan CPI for September (Fri 0830 JST; Thu 2330 GMT;
Thu 1930 EDT)
Consensus Forecast, CPI - Y/Y: 2.1%
Consensus Range, CPI - Y/Y: 2.1% to 2.3%
Consensus Forecast, Ex-Fresh Food - Y/Y: 2.1%
Consensus Range, Ex-Fresh Food - Y/Y: 2.0% to 2.3%
Consensus Forecast, Ex-Fresh Food & Energy - Y/Y:
2.3%
Consensus Range, Ex-Fresh Food & Energy - Y/Y: 2.2%
to 2.5%
Singapore CPI for September (Fri 1300 SGT; Fri 0500
GMT; Fri 0100 EDT)
Consensus Forecast, Y/Y: 2.4%
Consensus Range, Y/Y: 2.2% to 2.5%
CPI expected slightly higher at 2.4 percent in September
after 2.3 percent in August.
UK Retail Sales for September (Fri 0700 BST; Fri 0600
GMT; Fri 0200 EDT)
Consensus Forecast, M/M: -0.1%
Consensus Range, M/M: -0.5% to 0.1%
Consensus Forecast, Y/Y: 1.5%
Consensus Range, Y/Y: 0.7% to 2.0%
Sales expected to retreat by 0.1 percent on the month in
September after rising 0.5 percent in August.
France PMI Composite Flash for October (Fri 0815 CEST;
Fri 0615 GMT; Fri 0215 EDT)
Consensus Forecast, Manufacturing Index: 50.5
Consensus Range, Manufacturing Index: 50.0 to 50.5
Consensus Forecast, Services Index: 50.9
Consensus Range, Services Index: 50.2 to 50.9
The consensus sees manufacturing at 50.5 in the October
flash versus 50.6 in the September final. Services seen down slightly at 50.9
from 51.2.
Germany PMI Composite Flash for October (Fri 0930 CEST;
Fri 0730 GMT; Fri 0330 EDT)
Consensus Forecast, Composite Index: 53.1
Consensus Range, Composite Index: 52.8 to 53.6
Consensus Forecast, Manufacturing Index: 53.4
Consensus Range, Manufacturing Index: 53.0 to 54.0
Consensus Forecast, Services Index: 52.5
Consensus Range, Services Index: 52.2 to 53.0
The composite expected softer at 53.1 in the October flash
from 53.8 in the September final. Manufacturing seen down at 53.4 from 53.9 and
services at 52.5 from 52.9.
Eurozone PMI Composite Flash for October (Fri 1000 CEST;
Fri 0800 GMT; Fri 0400 EDT)
Consensus Forecast, Composite Index: 52.6
Consensus Range, Composite Index: 52.3 to 52.8
Consensus Forecast, Manufacturing Index: 52.6
Consensus Range, Manufacturing Index: 52.2 to 53.0
Consensus Forecast, Services Index: 52.5
Consensus Range, Services Index: 52.2 to 53.0
The composite expected softer at 52.6 in the October flash
from 53.1 in the September final. Manufacturing seen down at 52.6 from 52.9 and
services at 52.5 from 53.0.
UK PMI Composite Flash for October (Fri 0930 BST; Fri
0830 GMT; Fri 0430 EDT)
Consensus Forecast, Composite Index: 51.8
Consensus Range, Composite Index: 51.4 to 52.0
Consensus Forecast, Manufacturing Index: 51.7
Consensus Range, Manufacturing Index: 51.5 to 52.0
Consensus Forecast, Services Index: 51.8
Consensus Range, Services Index: 51.5 to 52.0
The composite expected marginally softer at 51.8 in the
October flash from 52.0 in the September final. Manufacturing seen at 51.7 from
51.9 and services at 51.8 from 52.1.
Canada Retail Sales for August (Fri 0830 EDT; Fri 1230
GMT)
Consensus Forecast, M/M: 1.3%
Consensus Range, M/M: 1.1% to 1.3%
Forecasters agree with Statistics Canadas projected 1.3
percent increase in retail sales for August from July.
US PMI Composite Flash for October (Fri 0945 EDT; Fri
1345 GMT)
Consensus Forecast, Composite Index: 57.6
Consensus Range, Composite Index: 57.0 to 58.0
Consensus Forecast, Manufacturing Index: 55.5
Consensus Range, Manufacturing Index: 55.0 to 55.6
Consensus Forecast, Services Index: 58.0
Consensus Range, Services Index: 56.5 to 58.4
The composite expected softer but still robust at 57.6 in
the October flash from 58.4 in the September final. Manufacturing seen down at
55.5 from 55.9 and services still booming at 58.0 from 58.8.
US Consumer Sentiment for October Final (Fri
1000 EDT; Fri 1400 GMT)
Consensus Forecast, Index: 46.3
Consensus Range, Index: 46.0 to 47.3
No revision expected from the very bad 46.3 in the October
preliminary, down 3.7 percent from September final and down 13.6 percent from a
year ago.
|